A Simple Roadmap to Sustainability Disclosure: Understanding the Roles of TCFD, ISSB, and SSBJ
"TCFD raised the issue, ISSB created the global standard, and SSBJ is adapting it for Japan." This single sentence provides the simplest overview of the current landscape of sustainability disclosure, a field that will shape the future of businesses. This article explains the complex relationship between these three organizations as one cohesive story.
You may have heard a lot about TCFD and ISSB recently and wondered what the difference is. These are key terms related to the new rules on how companies should report their environmental and social initiatives. Here, we'll break down the roles of each one simply.
The Beginning of the Story: TCFD
The TCFD (Task Force on Climate-related Financial Disclosures) was the starting point for all these discussions. The TCFD pioneered the idea that climate change is no longer just an environmental issue but a financial risk that could threaten a company's business. It proposed a framework with four core pillars (Governance, Strategy, Risk Management, and Metrics & Targets) for companies to report how they manage these risks to investors.
Creating a Global Standard: ISSB
As the TCFD’s ideas spread globally, a problem emerged: different reporting rules made it difficult for investors to compare companies. This is where the ISSB (International Sustainability Standards Board) came in. The ISSB’s goal is to create a single, unified benchmark—a "global baseline"—that companies worldwide can use. It builds upon the TCFD's framework, setting more detailed rules.
Japan's Response: SSBJ
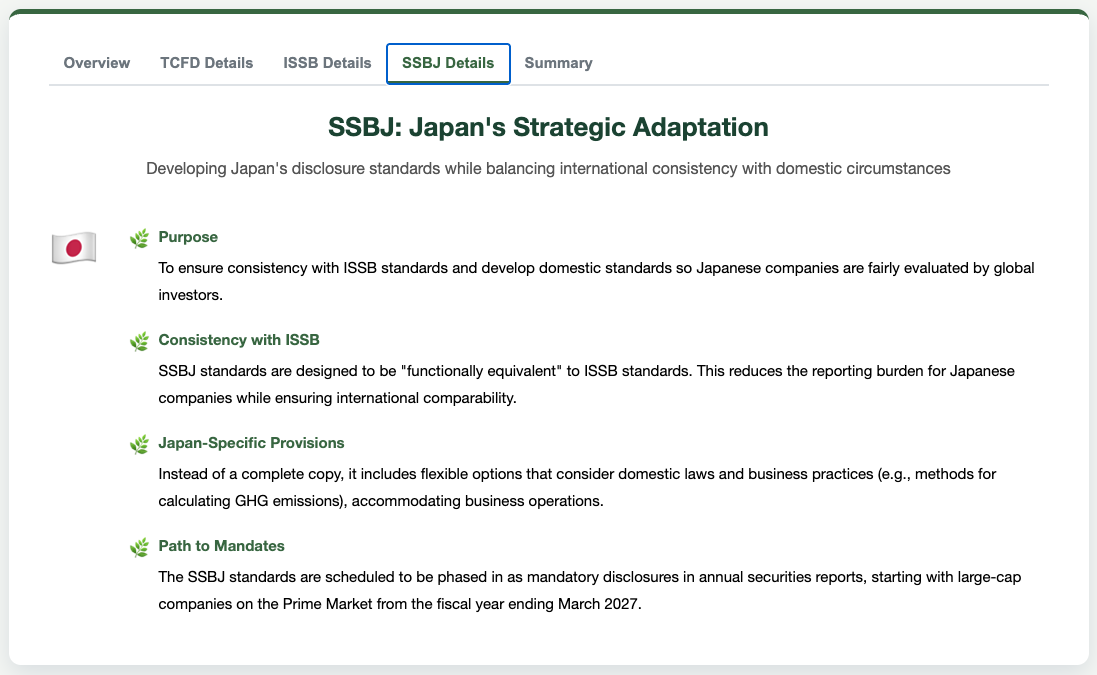
With a unified global standard from the ISSB now in place, the next challenge is how to apply those rules in Japan. This is the role of the SSBJ (Sustainability Standards Board of Japan). The SSBJ is developing an official set of domestic rules that are aligned with ISSB standards while also being adjusted to fit Japanese laws and business practices.
Conclusion
To summarize this flow: TCFD raised the issue, ISSB created the global standard, and SSBJ is adapting it for Japan. What was once a voluntary disclosure of sustainability information has now become a mandatory part of business strategy.
A Paradigm Shift: How TCFD Changed Climate Reporting
Climate Change Becomes a "Business Issue"
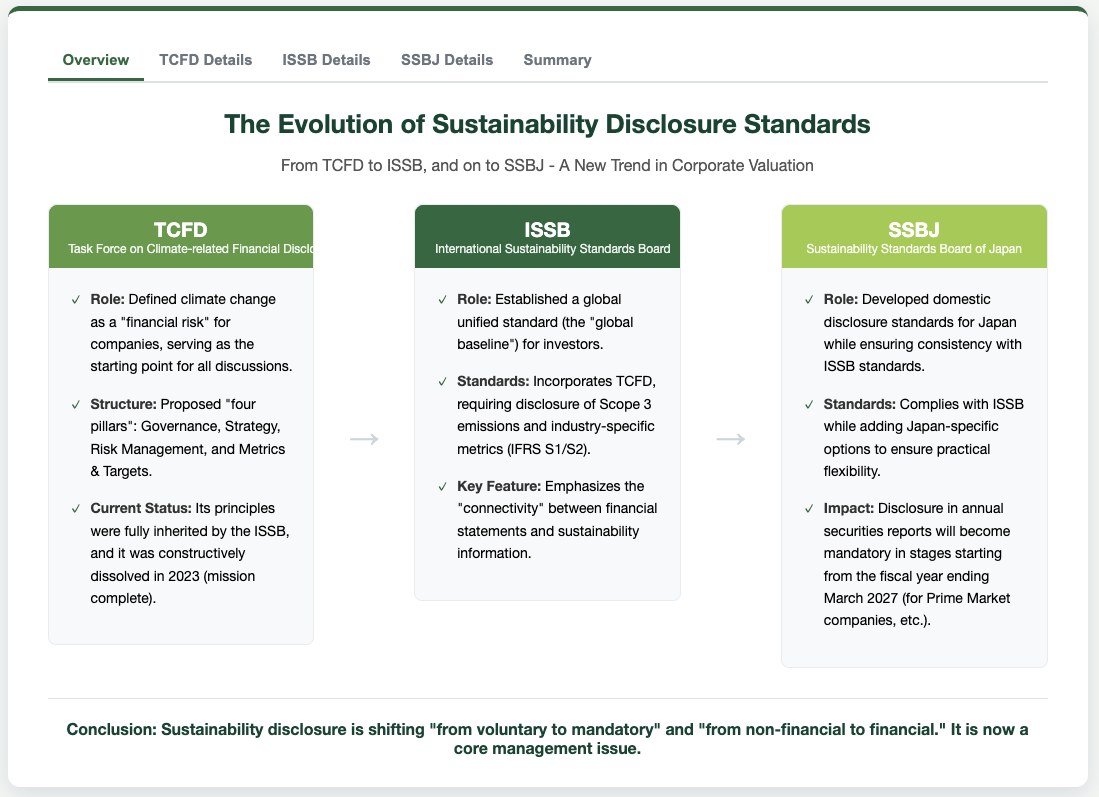
When did climate change stop being just an "environmental problem" and become a "financial risk"? The historical turning point was the emergence of the TCFD. TCFD built the foundation for modern sustainability reporting, fundamentally changing corporate norms.
Why TCFD Was Groundbreaking
Before the TCFD, climate change was mainly discussed in the context of corporate social responsibility (CSR). The TCFD redefined it as a "financial risk that threatens the stability of the financial system." It made it clear that events like a typhoon destroying a factory (physical risk) or stricter environmental regulations increasing costs (transition risk) could directly impact a company's profits and assets. This shift in perspective made investors and management see climate change as their own concern.
TCFD's Lasting Legacy: The "Four Pillars"
The TCFD proposed its powerful "Four Pillars" as a universal framework for companies to organize and report on climate-related risks and opportunities.
- Governance: How does leadership oversee this issue?
- Strategy: How will climate change affect the company’s business?
- Risk Management: How does the company identify and manage climate risks?
- Metrics & Targets: What metrics (e.g., CO2 emissions) are used to manage the issue and set targets?
This simple yet powerful framework was fully adopted by the subsequent ISSB standards, marking it as the TCFD's greatest contribution.
"Mission Accomplished": The TCFD's Dissolution
In 2023, the TCFD fully handed over its role to the ISSB and was dissolved. This wasn't an end but a "progressive dissolution," signifying that its principles have been adopted as the global standard.
Creating a Single Global Benchmark: What the ISSB Aims to Achieve
Putting an End to the "Alphabet Soup"
The ISSB was established with a monumental mission: to unite the scattered landscape of sustainability reporting under one global benchmark. It aims to provide the "comparable and reliable information" that investors need.
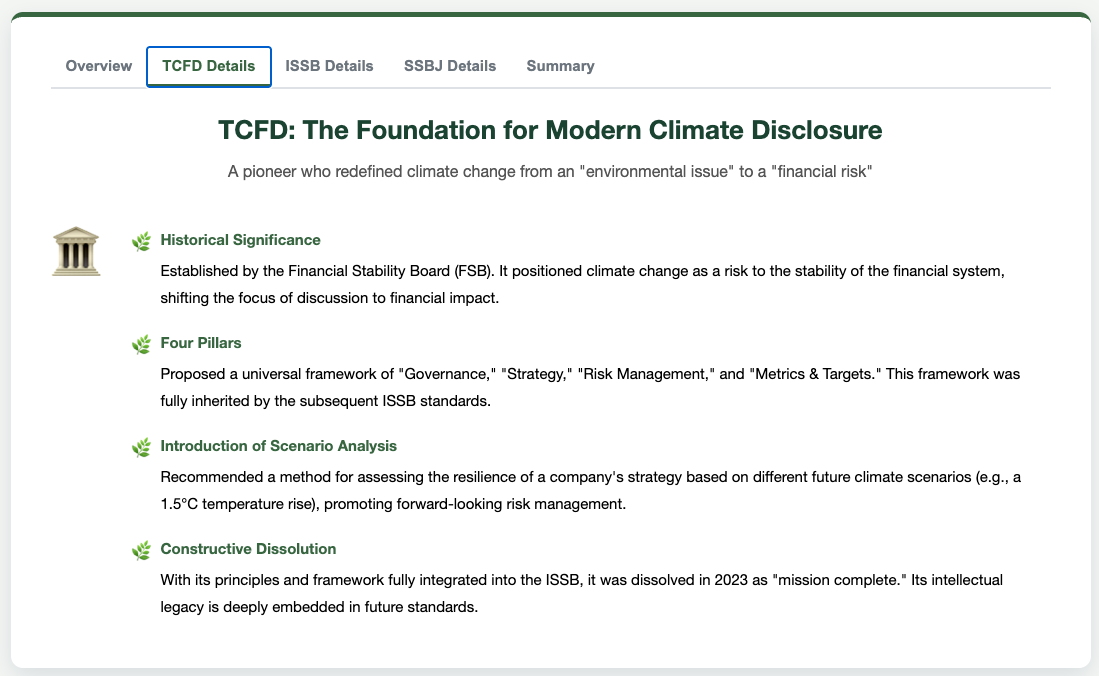
The world of sustainability reporting was once an "alphabet soup" of various standards. Investors found it difficult to compare companies, and companies didn’t know which standard to use. To resolve this confusion, the ISSB (International Sustainability Standards Board) was created.
The ISSB's Mission: Building a Global Baseline
The ISSB's primary mission is to create a high-quality, comparable "global baseline" for sustainability reporting that can be used across capital markets worldwide. This is a similar role to what IFRS (International Financial Reporting Standards) has done for financial accounting.
Evolution from TCFD
The standards released by the ISSB (IFRS S1/S2) build upon the TCFD’s framework while strengthening requirements in several ways.
- Fully Includes TCFD: The TCFD’s Four Pillars are completely integrated.
- Disclosure of Scope 3 Emissions: It generally requires companies to disclose CO2 emissions across their entire supply chain.
- Focus on Connectivity: It strongly emphasizes that companies must explain the connection between sustainability information and their financial statements (e.g., sales and profit).
Why It's So Important
By making ISSB standards the global norm, companies' sustainability efforts can be evaluated using the same yardstick. This is expected to attract more investment to companies with strong sustainability practices, steering the entire capital market toward a more sustainable future.
A Compass for Japanese Companies: The Role of the SSBJ
How Will Japan Address the Global Trend?
As a global standard (ISSB) emerges, Japanese companies aren't simply accepting it. The SSBJ plays a crucial and strategic role in balancing international alignment with domestic reality. As the compass guiding the future of Japanese disclosure, the SSBJ helps companies navigate this new landscape.
The Two Roles of the SSBJ
The SSBJ has two main responsibilities:
- Developing Domestic Standards: It develops a Japanese version of the sustainability disclosure standards that align with the ISSB's global standards while considering Japan's specific laws and business practices.
- International Advocacy: It actively participates in the ISSB's standard-setting process, acting as "Japan’s voice" to ensure the realities of Japanese industry are reflected.
Balancing "Alignment" and "Flexibility"
A key feature of the standards created by the SSBJ is their aim to be "functionally equivalent to ISSB standards." This prevents Japanese companies from being disadvantaged by global investors. At the same time, the SSBJ provides flexible options for certain items to accommodate Japanese business practices. This is a strategic approach to ensure companies can transition smoothly without falling behind the global trend.
The Path to Mandatory Disclosure
The standards developed by the SSBJ are expected to become mandatory, starting with large companies on the Prime Market for fiscal years ending in March 2027 and onward. For Japanese companies, sustainability disclosure is no longer an optional task but a fundamental part of their business strategy.